What classical portfolio theory actually says about borrowing
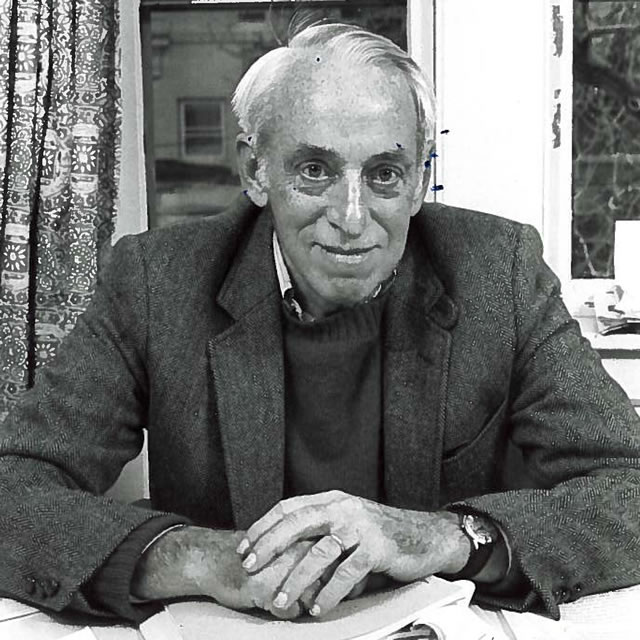
James Tobin, who won the Nobel Prize in Economics in 1981. He taught at Yale, served on President Kennedy's Council of Economic Advisers, and sat on the Federal Reserve's Board of Governors.
Markowitz published his model in 1952, and won the Nobel Prize in Economics for it in 1990. In that model some portfolios beat others. They earn more return for the same level of risk, or carry less risk for the same return. Plot those optimal portfolios and you get what he called the efficient frontier, on a graph that uses the variance of returns as the measure of risk.
His model leaves out both leverage and cash. What it did was lay the ground for everything that followed on what an optimal investment portfolio looks like.
The idea of borrowing to hold more of the best portfolio came from James Tobin, in 1958. Tobin won his own Nobel in 1981. He added one asset with no risk. The opportunity set stops being a curve. It becomes a straight line, later named the capital market line, starting at the risk-free rate and touching the efficient frontier at a single point. Everyone should hold the portfolio at that point. How much risk you want decides only how much cash you keep beside it. So an investor who finds that portfolio too risky should not hold all of it. He should hold 80% of it, or 50%, and leave the rest in the risk-free asset, where it earns the risk-free rate. And an investor who finds its return too low should borrow at the risk-free rate and hold more of that same portfolio than his own capital would buy.
So Tobin's answer to "I want more return" is not "buy something riskier". It is "buy more of the same thing, with borrowed money". William Sharpe built the Capital Asset Pricing Model on this in 1964, and shared the 1990 prize with Markowitz.
Tobin's picture. The frontier of risky assets is a hyperbola, turning back on itself at the minimum-variance portfolio. Add one riskless asset and the opportunity set becomes a straight line, touching the frontier at a single point: the tangency portfolio, the one with the best return per unit of risk. Every position an investor can take now sits on that line. Halfway along it, half the money is in cash and half in the tangency portfolio. At twice leverage the investor has borrowed an amount equal to their own capital, and by then the frontier has fallen well below the line, which is the theory's promise: borrowing against the best portfolio beats anything risky assets alone can offer. Notice the line is straight on both sides of the tangency point, which assumes borrowing costs exactly what lending pays.
Now look at the line again. It is straight. A straight line means one specific thing here: that borrowing costs exactly what lending pays. One rate, both directions, any amount. Nobody has ever been offered that rate. It is purely theoretical. This study closes the distance between that theory and actual practice. It models the spread over the base rate, the maximum loan-to-value, and the credit actually drawn. It also models how often the loan resets, how often the portfolio rebalances, and the running expenses of the funds themselves. And it models the margin call. That is the point where the loan breaches its agreed share of the collateral value, and the lender sells at that day's price.
Where the theory goes next, and where this study goes instead
Robert Merton took the question further. He worked out how much borrowing a rational investor should take on, once compounding is accounted for.
The closest thing in the literature to the question this piece asks is 1972 research by Fischer Black, on what happens when investors cannot borrow at the risk-free rate. Others have carried it further since. If you want the theory properly, the references are at the foot of this piece.
What I did here was narrower, but more practical for today's investors. I wanted to know what borrowing would have done to the seven model portfolios I built, over the ten years to 31 August 2026, using real funding rates and a real margin call rule. Not what an optimal borrower should have held. What these portfolios would have done: the return, the volatility, the worst drawdown, and whether the lender ever called the loan. For the ones that survived, how much room they had left before that point. All of it under assumptions you can change yourself, in the instrument I built for it: leveraged model portfolios.
Here is what happened.
The study, and what it found
The way I ran it is straightforward. I took the seven model portfolios I publish. They replicate passive strategies rather than active ones: no stock picking, only ETFs on broad indices, and no market timing beyond a quarterly rebalance back to target weights. The seven sit at seven points on the risk and return scale. At one end, a conservative portfolio holding nothing but fixed income, at low duration and low credit risk. At the other, an all-equity portfolio. Defensive, Permanent, Balanced, 60/40 and Offensive fall in between, in that order. Every one of those except 60/40 adds alternatives to the mix, gold above all: Harry Browne's Permanent Portfolio holds a quarter of its weight in it, and the Balanced and Offensive portfolios hold roughly a tenth. The chart below shows the ten-year backtest of these seven portfolios, with no borrowing, under the following assumptions: quarterly rebalancing and 2.0% a year in expenses.
The seven model portfolios, with no borrowing. Turn any line on or off in the legend, switch currency, and change the period, the simulated expenses or the rebalancing rule. The figures quoted in this article use the settings shown when the chart loads: US dollars, ten years to 31 August 2026, quarterly rebalancing and 2.0% a year in expenses. Over that decade Fixed Income returned -2.6%, Defensive 34.4%, the Permanent Portfolio 60.1%, Balanced 82.5%, 60/40 89.5%, Offensive 113.5% and Equity 179.5%. Fixed Income is the only one that finished below where it started, and that is the period rather than the strategy: it holds short duration and high credit quality, and 2022 fell on exactly that.
The assumptions fall into two groups: credit and portfolio.
Four of them concern the credit. How much of the portfolio's value is drawn as a loan. The maximum loan to value the lender allows. The spread charged over a base rate, which is SOFR for dollars, the euro short-term rate for euros, and SARON for francs. And how often the loan is reset back to its starting share of the portfolio. One detail there matters more than it looks: the base rate is floored at zero, because a Lombard contract floors it. SARON spent most of the decade below zero, so a Swiss borrower paid little more than the spread itself.
Two concern the portfolio: the annual running expenses, and how often it is rebalanced back to target weights.
Six variables across seven portfolios and three currencies is enough to turn any analysis into a mess. So the approach was deliberately simple. Start from assumptions that favour the borrower, and then tighten each one until borrowing stops beating the unleveraged alternative. Where that point sits, for each assumption, is the useful answer.
Here is what happened to the seven portfolios over the ten years from 31 August 2016 to 31 August 2026, borrowed against on terms most investors will never be offered. A maximum loan to value of 70%. A spread of 0.8% over the base rate, with the base rate floating daily and the loan reset to its target share of the portfolio every quarter. Annual portfolio expenses of 0.5%.
Start with which portfolios did not survive, because they faced a margin call. Nothing else matters once the lender has sold.
Equity broke first, everywhere. In dollars and in euros it was gone at 2.0x leverage, or 50% of the portfolio's value drawn as credit, sold on 16 and 18 March 2020, at the worst of the COVID crash. In francs it held to 2.2x (55%). Offensive followed, then 60/40 and Balanced together at 2.5x (60%), then Defensive and the Permanent Portfolio at 2.9x (65%). Fixed Income was never called at any leverage a lender would realistically extend. It breaks only at 3.3x (70%), and there the loan already sits at the ceiling on day one, so the arithmetic kills it rather than the market. Fixed Income has a different problem, and it is the only portfolio with it: over these ten years it earned less than the credit cost. It returned 1.24% a year in dollars against a loan costing 3.29%, and it lost money in euros and francs. Borrowing against it did not amplify a gain, it subtracted from one, so the leveraged version finished behind the unleveraged one at every level of credit. Two episodes did nearly all the damage elsewhere: the fourth quarter of 2018, and March 2020.
The counts run like this. Below 1.8x (45%), not one of the twenty-one portfolios was called. At 2.0x (50%), two. At 2.2x (55%), five. At 2.5x (60%), twelve, which is more than half. At 2.9x (65%), eighteen. At 3.3x (70%), all twenty-one.
The pattern is not gradual. Nothing happens at all until 2.0x (50%), and then almost everything happens between 2.0x (50%) and 2.9x (65%). The arithmetic behind it is plain enough: with a ceiling at 70%, a call comes after the assets fall by roughly one minus the drawn share divided by 70. At 2.0x (50%) that is a 29% fall, which March 2020 delivered to anything equity-heavy. At 2.5x (60%) it is 14%, which happens far more often than investors remember. Knowing where the calls happen is one thing. Knowing how close the survivors came is another. Take a moderate 1.4x (30% drawn), the level at which nothing was ever called. Across the ten years, at its worst moment, the all-equity portfolio was still 36% away from a call in dollars, 38% in euros and 41% in francs. The Permanent Portfolio kept between 52% and 54%. The median across all twenty-one was 48%. Whether a cushion of that size reads as comfortable or as uncomfortably thin is a question only the borrower can answer, and it is worth answering honestly before signing anything.
However, remember that all of this assumes the lender holds the line at 70% throughout. Lenders do not always oblige. A bank that grows nervous in a falling market can cut the advance rate on the same collateral, and it tends to do so at precisely the wrong moment. Suppose the line is cut to 50%. At the same moderate 1.4x (30% drawn), the buffer before a call would have dropped to barely 10% for the most aggressive all-equity portfolio in dollars, and to 13% and 17% for its euro and franc equivalents. In that situation you had better trust that your lender will not drop you at the moment you need him most.
Now back to the favourable assumptions: a 70% line, a 0.8% spread, 0.5% annual expenses, and a moderate 1.4x (30% drawn), in dollars. The table below sets each leveraged portfolio against its unleveraged twin.
Start with the bright side, because it is real. Borrowing did raise returns, and not marginally. The all-equity portfolio compounded at 15.5% a year with the loan against 12.5% without it, which over ten years is 321.3% against 224.8%. Every portfolio gained except one. Fixed Income is the exception described earlier: its returns never covered the cost of the credit, so borrowing turned 13.1% into 3.6%.
Then look at the two risk columns, and the bright side dims. The same equity portfolio fell 48.4% at its worst instead of 34.1%, both on 23 March 2020, at the bottom of the COVID crash. Volatility rose from 17.2% to 25.4%. Put plainly: three extra percentage points of annual return were bought with eight points of volatility and fourteen points of drawdown.
| Portfolio | Total return | Annualised | Volatility | Max drawdown | Margin left |
|---|---|---|---|---|---|
| Fixed Income | 13.1% | 1.2% | 2.0% | -9.2% | no borrowing |
| with 1.43x leverage | 3.6% | 0.4% | 2.8% | -13.9% | 56% from margin call |
| Defensive | 56.1% | 4.6% | 5.5% | -16.3% | no borrowing |
| with 1.43x leverage | 62.5% | 5.0% | 7.9% | -23.3% | 52% from margin call |
| Permanent Portfolio | 86.1% | 6.4% | 7.7% | -19.0% | no borrowing |
| with 1.43x leverage | 107.5% | 7.6% | 10.9% | -26.8% | 52% from margin call |
| Balanced | 112.0% | 7.8% | 9.4% | -21.1% | no borrowing |
| with 1.43x leverage | 146.6% | 9.4% | 13.5% | -29.6% | 48% from margin call |
| 60/40 | 120.2% | 8.2% | 11.0% | -23.6% | no borrowing |
| with 1.43x leverage | 157.1% | 9.9% | 15.9% | -33.0% | 46% from margin call |
| Offensive | 148.1% | 9.5% | 11.7% | -23.8% | no borrowing |
| with 1.43x leverage | 203.4% | 11.7% | 16.9% | -33.8% | 45% from margin call |
| Equity | 224.8% | 12.5% | 17.2% | -34.1% | no borrowing |
| with 1.43x leverage | 321.3% | 15.5% | 25.4% | -48.4% | 36% from margin call |
USD portfolios, 31.08.2016 to 31.08.2026. Each strategy is shown twice: on its own, then with 1.43x leverage, meaning 30% of the portfolio value drawn as credit. Maximum loan to value 70%, spread 0.8% over overnight SOFR floored at zero, portfolio expenses 0.5% a year, leverage reset and rebalancing both quarterly. The last column is how much further the assets could have fallen, at the worst moment of the decade, before the lender would have sold.
That comparison, each portfolio against its own borrowed twin, is not the one Tobin was making. His claim was sharper. If you want more return, he said, do not buy a more aggressive portfolio. Borrow against the best one instead.
That is a testable proposition, and the study tests it directly. Take a lower-risk portfolio, borrow against it until it reaches a higher-risk portfolio's return, and then ask which of the two carried less risk getting there. To count as a win, the borrowed version has to be at least as good on all three measures at once: return, volatility and worst drawdown. No trade-offs.
In dollars it almost never worked. Across 133 combinations of portfolio and credit level, during the ten years to 31 August 2026, exactly one leveraged portfolio beat an unleveraged one outright, and it is so slight that no one would act on it: borrowing 10% against Balanced beat holding 60/40 by 0.7 percentage points of total return over ten years, with 0.6 points less volatility. That is seven hundredths of a percent a year. The reason a leveraged Balanced portfolio edged past 60/40 at all has less to do with the loan than with what the two portfolios hold: Balanced carries roughly a tenth of its weight in gold, 60/40 carries none, and gold returned 227% over the decade while diversifying the equity risk beside it.
Everywhere else, reaching for a higher return by borrowing cost more than simply owning the riskier portfolio. To match the all-equity return from Offensive took 1.67x, and at that point the borrowed version carried 19.9% volatility against 17.2% and a 39.3% drawdown against 34.1%. Same destination, worse journey, and a margin call 26% away rather than comfortably out of sight.
Change the currency and the answer changes with it. In euros, borrowing won three times. In francs, four. Against one in dollars.
Most of those wins look alike. A small loan, between 1.1x and 1.3x, taken against the Permanent Portfolio or Balanced, reaching past 60/40 or Balanced. Each one finished 61% to 92% clear of a margin call, so none of them ever came close to being sold. The pattern from the dollar case repeats: 60/40 is the rung being stepped past, in every currency.
The franc holds the one case in this study where borrowing beat the top of the ladder. Offensive at 1.4x returned 138.8% against the all-equity portfolio's 134.9%, with lower volatility, 12.8% against 13.9%, and a shallower drawdown, 29.9% against 30.4%. Better on all three, with 47% still to spare before a call. That is Tobin's prescription working precisely as he wrote it.
Two things made the difference, and neither of them is the loan. Funding was far cheaper: SARON spent most of the decade below zero, and a Lombard contract floors the base rate at zero, so a Swiss borrower paid 1.13% a year all in, against 1.92% in euros and 3.29% in dollars. And the ladder was ordered differently. In dollars the all-equity portfolio earned the most per unit of risk, so there was nothing better to borrow against. In francs it did not: Offensive earned 10.6 per unit of volatility against Equity's 9.7. Swiss-franc equity returns were weak enough over this decade that a diversified portfolio holding gold simply beat them, and borrowing against the better portfolio then did exactly what the theory promises.
Which is the finding, stated plainly. Tobin was not wrong. His prescription pays whenever a lower-risk portfolio genuinely earns more per unit of risk than the one above it, and costs money whenever it does not. Whether that condition holds is not a matter of theory. It depends on the decade, the currency, and what the portfolios happen to own.
What survives examination
Borrowing did raise returns, in almost every portfolio and every currency. It raised volatility and drawdowns by more. And it introduced a risk the unleveraged investor never carries at all: at 2.0x, two portfolios had to be sold because they faced a margin call, within a week of the March 2020 bottom, and at 2.5x, twelve of twenty-one were sold for the same reason.
Where borrowing genuinely improved a portfolio, it did so in small doses, between 1.1x and 1.4x, and only where a lower-risk portfolio was already earning more per unit of risk than the one above it. Borrowing did not create that advantage. It leaned on one that was already there, put there by what the portfolio held rather than by what it owed.
Which returns us to the arithmetic at the start. A portfolio making 8%, money costing 3%, borrow another half, expect something near 10.5%. That sum was never wrong. It simply answered a question about one average year, when the question worth asking was what happens to a particular pile of money, over a particular decade, with a lender who has an opinion about it.
Sources
Markowitz, H. (1952). Portfolio Selection. The Journal of Finance, 7(1), 77-91.
Kelly, J. L. (1956). A New Interpretation of Information Rate. Bell System Technical Journal, 35(4), 917-926.
Tobin, J. (1958). Liquidity Preference as Behavior Towards Risk. The Review of Economic Studies, 25(2), 65-86.
Sharpe, W. F. (1964). Capital Asset Prices. The Journal of Finance, 19(3), 425-442.
Merton, R. C. (1969). Lifetime Portfolio Selection under Uncertainty: The Continuous-Time Case. The Review of Economics and Statistics, 51(3), 247-257.
Black, F. (1972). Capital Market Equilibrium with Restricted Borrowing. The Journal of Business, 45(3), 444-455.
Avellaneda, M. and Zhang, S. (2010). Path-dependence of Leveraged ETF Returns. SIAM Journal on Financial Mathematics, 1(1), 586-603.
Frazzini, A. and Pedersen, L. H. (2014). Betting Against Beta. Journal of Financial Economics, 111(1), 1-25.